Smart real estate asset management
Building a robust property portfolio requires more than capital; it demands a deep understanding of real estate market cycles and legal frameworks. Successful investors analyze local property trends to maximize appreciation while mitigating risks associated with economic fluctuations, structural depreciation, and evolving urban planning regulations within the target area.
Navigating the apartment purchase process
Securing the ideal property
The acquisition phase begins by defining clear property criteria for location and amenities to filter the market effectively. Buyers must then secure mortgage preapproval to strengthen their negotiating position before attending property viewings and submitting a formal purchase offer for the selected unit.
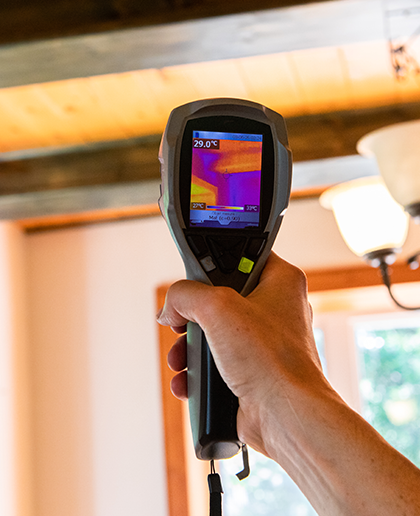
Conducting thorough property inspections
Professional property inspectors assess structural integrity and identify hidden plumbing defects or electrical system issues before closing the deal.
Understanding co-ownership regulations
Reviewing building bylaws reveals renovation restrictions or limits on short-term rentals that could affect future usage rights.
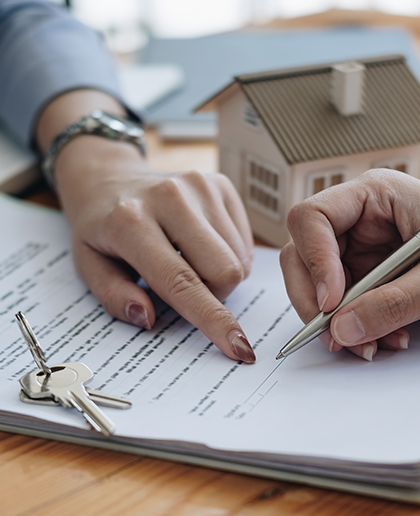
Finalizing the deed of sale process
The notary ensures a legally binding transfer of title and officially registers the transaction with the relevant authorities.
Optimizing value when selling
Achieving the highest possible price requires a strategic approach to property presentation and marketing channels. Home staging transforms cluttered spaces into inviting environments where potential buyers can picture themselves living. At the same time, pricing the unit according to a comparative market analysis helps generate immediate interest and avoid listing stagnation, which often leads to price reductions and reduced bargaining power during the final negotiation stages.
Strategies for profitable rental investment
Generating consistent rental cash flow depends on selecting high-demand locations and careful tenant screening to minimize vacancies. Investors calculate gross and net yields to determine whether rental income covers mortgage payments and maintenance costs while building long-term equity through debt pay-down.
Securing competitive real estate financing
Leverage remains a powerful tool in property acquisition, allowing investors to control significant assets with limited equity input. Comparing mortgage products requires looking beyond the interest rate to assess term flexibility, prepayment privileges, and penalties. Fixed rates provide stability for long-term planning, while variable rates may offer lower initial costs but carry interest rate fluctuation risk during the loan amortization period, directly affecting monthly cash flow.
Managing real estate fiscal implications
Understanding the tax burden
Fiscal obligations can significantly affect real estate profitability and require careful planning. Investors must account for property transfer costs as well as recurring annual liabilities that fund municipal services and school boards within the jurisdiction where the property is located.
Transfer duties and acquisition fees
Commonly known as the « welcome tax, » this one-time levy is calculated based on the property’s assessed value or purchase price.
Deductible Operating Expenses
Owners can reduce taxable income by deducting mortgage interest, insurance premiums, and maintenance costs incurred during the fiscal year.
Capital gains tax treatment
Selling a secondary residence or investment property triggers taxation on the realized capital gain between the purchase and sale price.